ई-कॉमर्स
Social Media से Sales: Campaign, Scheduling और AI Prompts
Social Hub से content schedule और Meta campaigns review करें। चार AI prompts के साथ ecommerce और ERP records से marketing का असली परिणाम समझें।
Anichur Rahaman2 घंटे पहले7मिनट
दस markets के current official checkpoints और structured data, validation, delivery, correction व payment तक practical invoice guide।
लेखक
Anichur Rahaman
Wholesaler का customer structured invoices माँगता है। Finance manager साफ PDF भेज सकती हैं, लेकिन buyer system को process करने योग्य tax identifiers, line amounts और purchase reference चाहिए। पहला काम सुंदर invoice बनाना नहीं, existing business data सही पहुँचाना है।
Wholesaler teaching example है। मानें महीने में 600 invoices और हर retyping में दस मिनट: 100 घंटे potential work। यह measured saving नहीं। Structured exchange कुछ re-entry कम कर सकता है, पर cleanup, review, exceptions और connection support में समय रहता है।
इस guide के selected official requirements 5 नवंबर 2026 को जाँचे गए हैं। Legal scope, software capability, delivery acknowledgement और actual payment अलग हैं। Country checkpoints शुरुआती map हैं, सभी obligations/exemptions की पूरी सूची नहीं।
Structured e-invoice में defined machine-readable fields होते हैं। Structured data माँगने वाले mandate में सामान्य emailed PDF पर्याप्त नहीं। EN 16931 European semantic model है; UBL और UN/CEFACT CII उसकी syntaxes हैं। Destination को specific profile, version या local extension चाहिए हो सकता है, कोई भी XML नहीं।
Hybrid Factur-X/ZUGFeRD में readable PDF और structured XML साथ हैं। Qualification accepted version/profile और applicable rules पर है; arbitrary XML attach करने से compliance नहीं। दोनों representations मिलाएँ और legally required original components रखें।
Format, exchange network और tax reporting अलग layers हैं। Peppol के चार corners sender, sender access point, recipient access point और recipient हैं; authority reporting साथ हो सकती है। Clearance में issuance path पर authority validation है; post-audit में वही pre-clearance नहीं। Countries models mix करते हैं, ये तीन mutually exclusive products नहीं। Actual profiles/rules official Peppol BIS Billing documentation में देखें।
उदाहरण: Saudi standard tax और simplified invoices का clearance/reporting अलग है। सभी के लिए “पहले tax authority, फिर buyer” flow गलत होगा। Actual document type, route और reporting obligation देखें; ZATCA technical guide यह फर्क बताती है।
Legal seller/buyer, establishment/VAT status, domestic/cross-border supply, B2B/B2C/B2G, exemptions और turnover basis पहचानें। Receive, issue, report, provider appointment और penalty relief की dates अलग हो सकती हैं। Customer preference अपने आप हर supplier का statutory mandate नहीं।
Table original लेख के दस markets रखती है, लेकिन unqualified global date के बजाय current official links देती है। Entity के earlier wave/exception से जवाब बदल सकता है। Scope किसने verify किया और review कब होगा, लिखें; timeline screenshot हमेशा सही नहीं रहता।
कई dates आ चुकी हैं। Small business होना receiving duties अपने आप खत्म नहीं करता। Summary में कई sector/transaction/entity exceptions नहीं हैं; applicable detail के लिए authority link खोलें।
| Market / Official Source | Current Checkpoint और जरूरी Scope |
|---|---|
| Germany | Domestic B2B receiving 1 Jan 2025 से। Issuing सामान्यतः prior-year turnover>€800,000 पर 1 Jan 2027, अन्य eligible cases 1 Jan 2028; exemptions/EDI transition लागू। Small-business issuance exemption receiving नहीं हटाता। |
| Belgium | In-scope domestic B2B structured exchange 1 Jan 2026 से। Peppol default route है; agreed compliant alternative और statutory exceptions अलग जाँचें। केवल “Peppol recommended” नहीं। |
| Croatia | Domestic B2B: VAT-system taxpayers 1 Jan 2026 से issue/receive और fiscalisation। Relevant non-VAT taxpayers 2026 में receive,1 Jan 2027 से issue। |
| Poland | KSeF receiving 1 Feb 2026;2024 VAT-inclusive sales>PLN 200m में issuance 1 Feb, अन्य 1 Apr। Monthly invoiced gross≤PLN 10,000 में transitional conditions पर 2026 अंत तक defer हो सकता है। |
| France | In-scope receiving 1 Sep 2026; large/ETI तभी issue, SME/micro 1 Sep 2027 से। ETI SME category नहीं। Approved platforms और separate e-reporting scope देखें। |
| Spain | Order HAC/1028/2026 effective 6 Oct 2026 से clock शुरू: prior-year turnover>€8m पर 6 Oct 2027, अन्य 6 Oct 2028। Payment-status reporting की और phases हैं; order pending नहीं। |
| UAE | In-scope revenue≥AED 50m: ASP appointment 30 Oct 2026, implement 1 Jan 2027। Lower cohort appointment 31 Mar 2027, implement 1 Jul 2027; government 1 Oct 2027। Current exclusions और pilot अलग देखें। |
| Saudi Arabia | Wave 25:2022–2025 के किसी वर्ष VAT-subject revenue>SAR 187,500; notified integration 1 Feb 2027 तक। Earlier-wave duties कायम; अपने notice और invoice-type clearance/reporting देखें। |
| Malaysia | Current HASiL exemption annual turnover/revenue<RM 3m, related-entity/shareholder exceptions सहित। Phase 4 सामान्यतः 1 Jan 2026; new-business dates अलग। Conditional relaxation 31 Dec 2027 तक Guidelines 4.8/Specific 4.9 देखें। पुराना RM 1m headline outdated। |
| European Union | ViDA cross-border B2B digital reporting mandatory e-invoicing के आधार पर 1 Jul 2030 से। Earlier domestic mandates जारी; universal 2026/2028 start नहीं। |
Spain के अलग billing-software/SIF rules, VERI*FACTU options सहित, B2B exchange dates नहीं हैं। Consolidated RD 1007/2023 schedule specified corporate-tax cohort के लिए 1 January 2027 और other in-scope taxpayers के लिए 1 July 2027 देता है।
Malaysia में Guideline 4.8,1.5–1.6 और Specific 4.9,16 देखें। Relaxation conditional है, सब requirements से exemption नहीं। UAE amended Decision 66/2026 AED 50m-and-above boundary और appointment date confirm करता है।
Controlled invoice record में legal parties, tax determination, units, quantities, prices, allowances, currency, dates, terms और routing/buyer references हों। उससे structured file और readable view बनाएँ, फिर दोनों validate करें। Shared source mismatch घटाता है, rounding/formatting bugs असंभव नहीं करता।
केवल arithmetic example: तीन units at 30, subtotal 90;10% line discount 9 और taxable net 81। Assumed tax 20% पर tax 16.20, total 97.20। यह किसी market की tax advice नहीं। Required line/header rounding, allowances और tax categories जाँचें; XML parse होना पर्याप्त नहीं।
Missing buyer reference, invalid identifier और गलत tax treatment की correction अलग हो सकती है। कुछ references profile/customer requirement हैं, universal fields नहीं। Tax actual transaction/parties पर है, product की fixed rate मात्र पर नहीं। जहाँ authoritative checks हों tax IDs validate करें और routing/bank changes control करें।
Outbound conversion या inbound extraction हमेशा गलत नहीं, लेकिन verified mapping चाहिए। Original approved data उपलब्ध हो तो पहले PDF बनाकर OCR से वापस निकालना avoidable reconstruction step है।
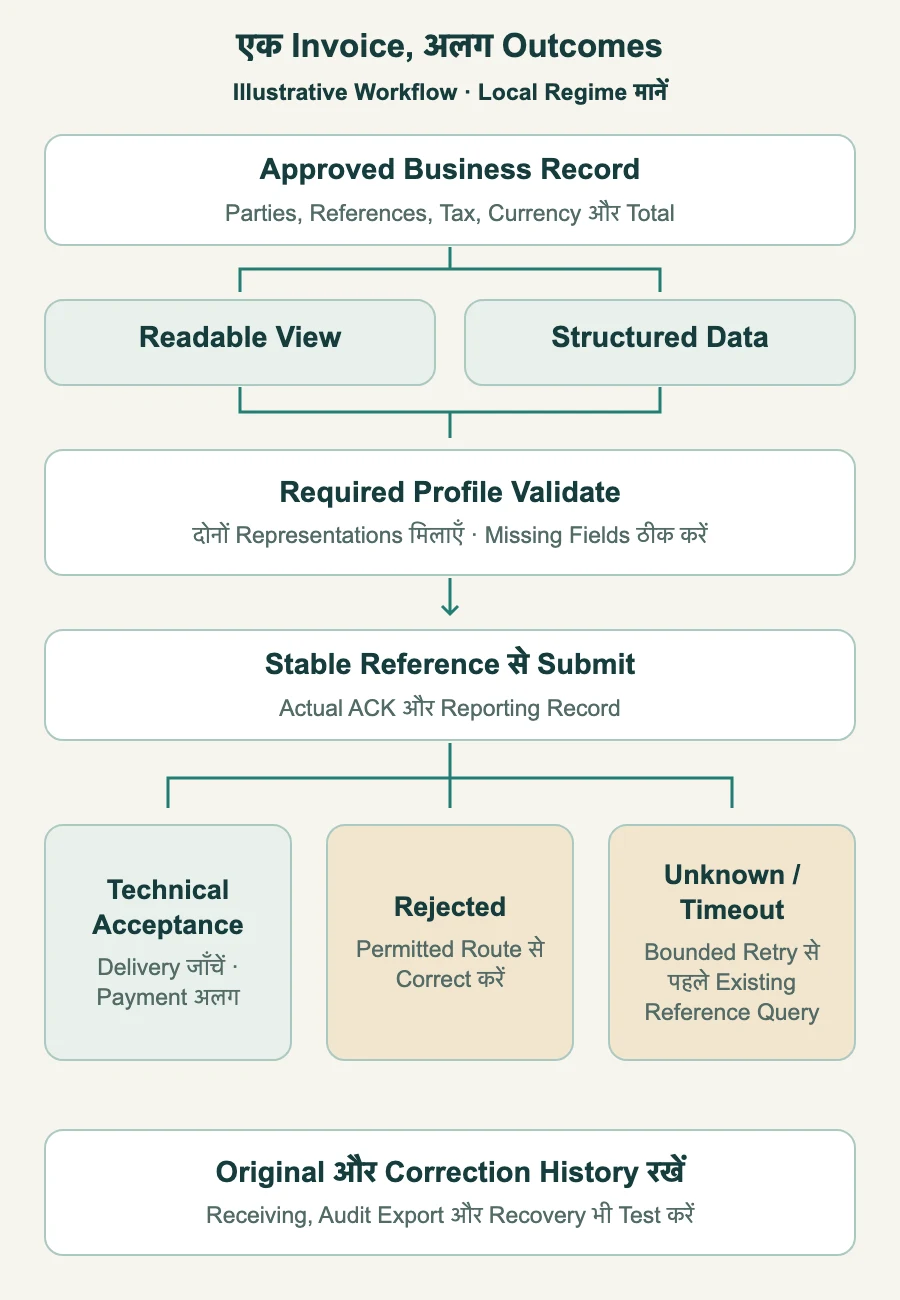
Immutable business reference, provider/authority IDs और status history रखें। Local validation, submission, technical acceptance, delivery, buyer response और payment अलग facts हैं। Authority acceptance commercial correctness, payment approval या paid होने का प्रमाण नहीं।
Timeout पर resubmit से पहले existing reference query करें। Duplicate protection, retryable outages में bounded backoff और exception owner हों। Unknown outcome में चुपचाप नया invoice number न बनाएँ। Invalid data/credentials ठीक करें, वही rejection बार-बार send नहीं।
Issued/accepted invoice में permitted window cancellation, correction document, credit/debit note या prescribed references वाला replacement चाहिए हो सकता है। Regime/error के अनुसार तरीका बदलता है; हर change “credit note plus new invoice” नहीं। Original evidence और authorised corrections रखें, history delete न करें।
हर regime का lawful outage/offline process और reporting deadline तय करें। Generic fallback PDF या delayed retry हमेशा allowed नहीं। Buyer को document मिल जाए तब भी separate reporting track करें।
Incoming file सही legal entity/AP queue में पहुँचे, render/validate हो, supplier/order/receipt से match हो और exceptions का owner हो। Receive करने से tax, payment या supplier-bank change automatically approve नहीं होता।
Attachments untrusted input हैं। Controlled parsing, malware protection और restricted storage लें; invoice public marketing image नहीं। Staff/AI access role/entity से सीमित करें। Applicable period तक originals, required components, acknowledgements और corrections रखें।
Provider exit सहित readable audit export और restore जाँचें। Provider portal या backup अकेले retention/integrity/accessibility compliance का proof नहीं। एक worldwide retention period नहीं है।
Finance scope/tax का, sales/master-data owner customer details का, operational owner connection, credentials, renewal और outages का जिम्मेदार हो। Onboarding, per-document charges, support, export, service levels और exit terms compare करें। “E-invoicing ready” badge हर country की accredited connection सिद्ध नहीं करता।
Permitted test environment में ordinary sales, discounts, partial credit notes, cancellation/correction, foreign parties, missing buyer reference, duplicate sends, expired credentials, timeouts और incoming invoices चलाएँ। Actual acknowledgement, legal reference, reporting और archive retrieval देखें, केवल successful PDF नहीं।
कानून अनुमति दे तो controlled customers से शुरू करके reconciliation/training के बाद बढ़ाएँ। Duration scope, data और provider onboarding पर है; एक quarter universal promise नहीं। Mandatory date से पहले authorised manual exceptions और पर्याप्त capacity हों।
Verified re-entry time, review/support effort, rejection reasons, unresolved age और valid delivery तक समय मापें। Late-payment behaviour और cash savings अलग रखें। Wholesaler का 100-hour case baseline assumption है;100 घंटे गायब होने या customer जल्दी pay करने का proof नहीं।
Finance manager एक invoice का demonstration माँग सकती हैं: क्या approved data से मिलता है, सही route से buyer तक पहुँचता है, status सही है, और बाद में correction/retrieval हो सकता है? Incoming invoice पर भी यही evidence लें।
यह “XML export करता है” से मजबूत buying criterion है और अगली rule, customer reference या connection change पर clear owner छोड़ता है।
समीक्षा: 5 नवंबर 2026। Anichur Rahaman StoreConsole के निर्माता हैं। Wholesaler, workload और tax arithmetic teaching examples हैं; selected checkpoints किसी entity की सभी obligations का complete determination नहीं।
लेखक का परिचय
Anichur Rahaman
पढ़ना जारी रखें